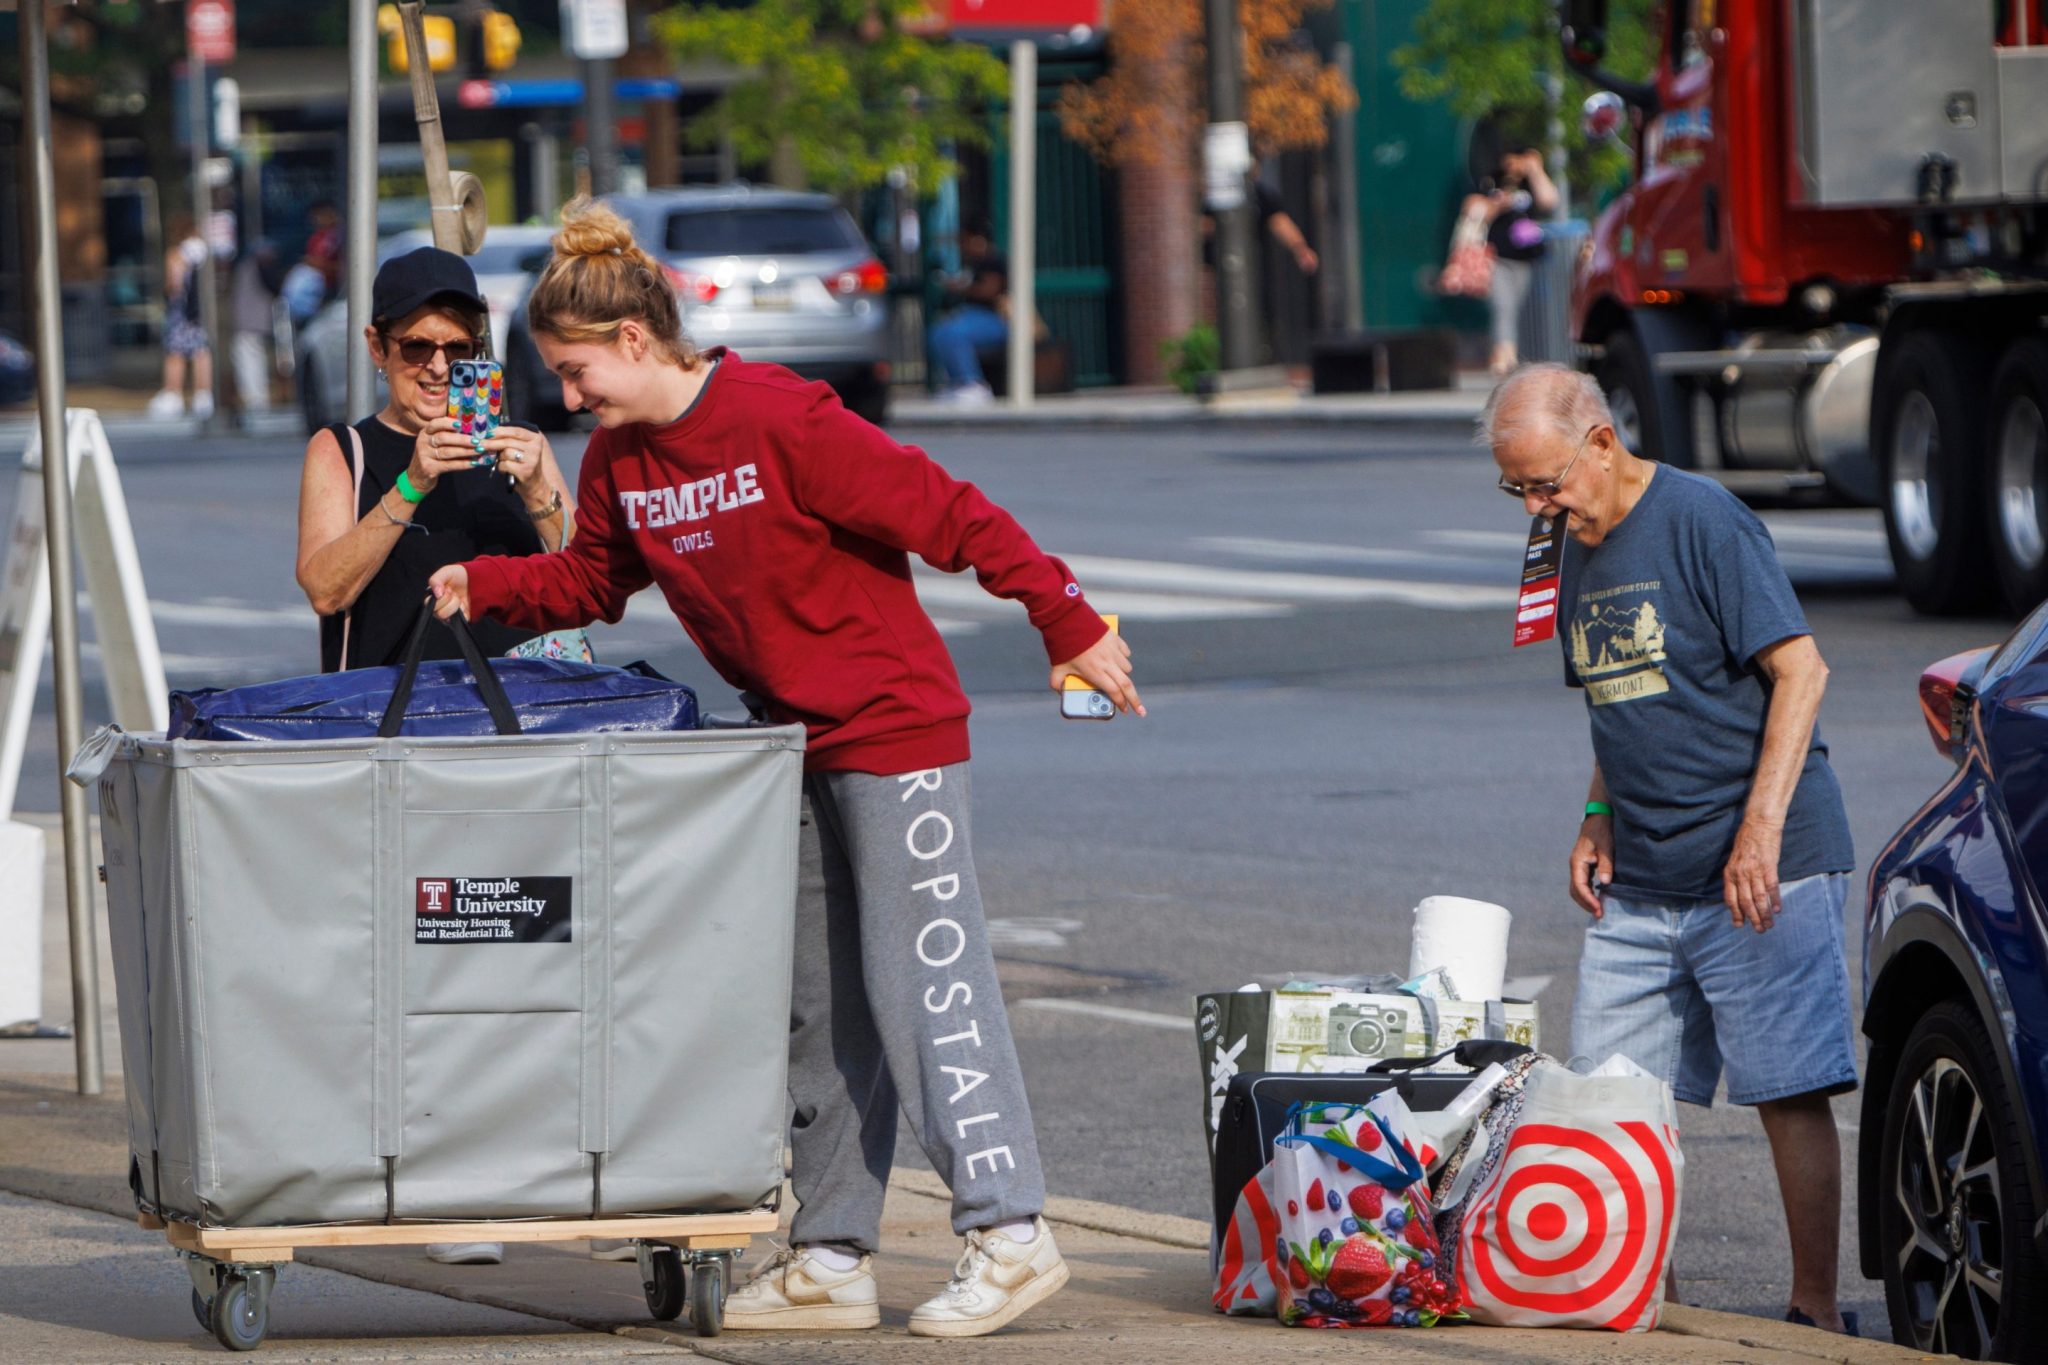
Heading off to college is thrilling, but it also comes with grown up responsibilities. Among the most important is learning how to handle money. Financial experts say the decisions students make now can shape their financial security long after commencement.
Experts emphasize that building a solid financial foundation starts with credit. Sara Wilson, director of product innovation at Student Connections, an organization that helps students overcome financial barriers, said the choices made in college directly affect future financial well being. “You have to consider the financial decisions you make in college because they impact what your financial security is going to be once you enter your first job,” Wilson said.
Courtney Alev, consumer financial advocate at Credit Karma, recommends starting with secured credit cards, which require a one time deposit that serves as collateral. That deposit is typically returned when the account is closed with a zero balance or when the user upgrades to an unsecured card. Student credit cards are another option, often easier to qualify for and with lower limits. Alev said a credit score, which ranges from 300 to 850, is a mathematical tool lenders use to assess repayment likelihood. A low score can make loans, mortgages, insurance and other services more expensive or harder to obtain. “College is an ideal time to start building a credit report, because the earlier you start, the more time you have for that credit to build and then work in your favor when you eventually need it, whether it’s for a loan or an apartment,” Alev said. The most important rule, she added, is to only charge what you can pay off in full each month.
Budgeting is another crucial step, even when income comes from multiple or irregular sources like part time jobs, financial aid stipends or family support. Wilson said budgeting is about creating a plan to reach your goals. “Budgeting is simply creating a plan to get what you want with your money,” she said. “Figuring out what you want, then the plan that you need to follow to get there.” Apps, spreadsheets or paper all work, as long as earnings and spending are tracked. To handle uneven income, Lindsay Bryan-Podvin, financial therapist and founder of Mind Money Balance, suggests dividing monthly bills by four. For instance, if rent is $1,000 due on the first, save $250 each week. This method helps when income arrives inconsistently.
Before diving into investing, students should build an emergency fund. Alev noted that while compounding interest is powerful over time, immediate needs come first. “The power of that compounding interest and the growth of the economy can really pay off over time, and it’s so important, but an emergency fund is going to serve your immediate needs,” Alev said. She suggests saving enough to cover rent and essentials for a few months before investing.
College also brings new social circles, and money can become an awkward topic. Bryan-Podvin encourages open communication about financial boundaries. “It can feel really hard to say ‘I can’t afford that or that’s not a priority for me,’” she said. Being transparent helps avoid pressure to overspend. Setting clear spending priorities, like keeping a gym membership because it brings value, can make it easier to decline other expenses such as ordering takeout with roommates.
Student loans require a clear plan, even though repayment starts after graduation. Wilson advises knowing how much you borrow each semester, the expected total repayment amount, and what monthly payments will be. “As long as you understand what you’re getting into and you’re making a plan for how to navigate and manage it, you’re an informed consumer of that debt,” Wilson said. Delaying this understanding can have lasting financial consequences.
While in school, students should take advantage of free resources on campus, whether in the library, student life office or recreation center. Phil Schuman, executive director at the Higher Education Financial Wellness Alliance, said these services are nonjudgmental. “The nice thing about the system that you have on your campus is the people aren’t going to judge you,” Schuman said. “Their job is to help you figure out what the solution is to your question, and they’re going to point you in the right direction.”
Mistakes are inevitable, but Schuman emphasized the importance of coping with them. “Mistakes will happen,” he said. “Give yourself grace. Nobody is perfect when it comes to their finances, so don’t feel like you have to be as well. Talk to somebody, acknowledge it, and then figure out what you can do moving forward to right the wrong next time.”
Managing personal finances is a lifelong learning process, but starting in college can set a strong foundation. By making informed choices about credit, budgeting, saving and borrowing, students can enter their first jobs with greater financial confidence.